From Traditional Banking Apps to Transactional Banking With Agentic AI
For years, banks’ mobile apps have followed much the same pattern: menus, options, forms, buttons, structured screens, and predefined workflows.
Users log in, look for an option, navigate through several screens, fill in fields, confirm the details, and finally complete a transaction.
This model has worked. In fact, it has been instrumental in digitizing many financial services that once required a branch visit, a phone call, or a manual process.
But we’re entering a new phase.
Advances in artificial intelligence, especially agentic AI, could profoundly change how end users interact with banking systems.
Users can do more than just “navigate” an app.
They can “have a conversation,” make requests, confirm details, and complete transactions more naturally and directly.
Imagine a banking app where users can skip the menus and simply type or say:
“Show me how much I spent on groceries this month.”
“Transfer Q500 to my mom.”
“Pay my credit card on Friday.”
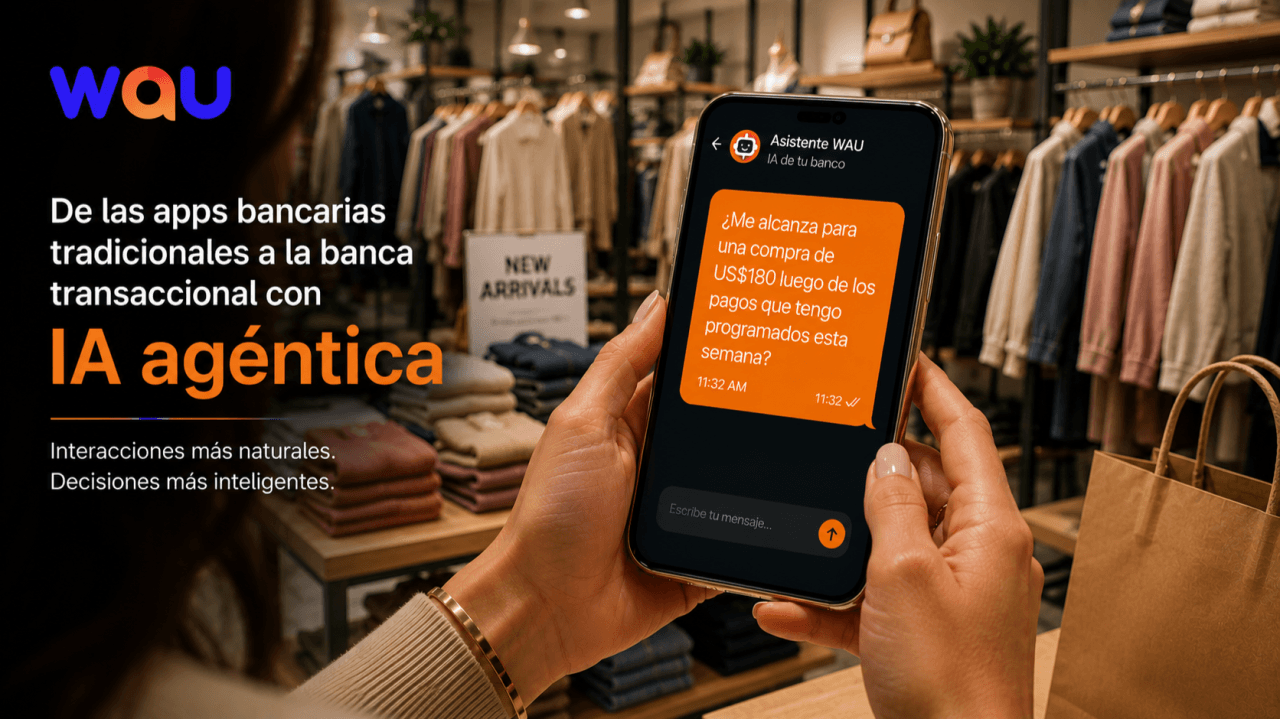
“Do I have enough in my account to cover my recurring payments this week?”
“Schedule my tuition payment every month.”
In this model, the banking app evolves from an interface for navigating menus into an intelligent layer for carrying out transactions.
The experience shifts from structured to contextual.
From reactive to proactive.
From menu-driven to intent-driven.
In my view, this is one of the most significant changes we’ll see in digital banking in the next few years.
But a conversational experience alone isn’t enough
There’s an important point to keep in mind.
Putting a conversational interface or an AI agent in a banking app takes more than connecting a language model to the mobile app.
Treating it that way would be a mistake.
In banking, an inquiry can trigger more than a simple lookup.
A transfer involves more than giving an instruction.
A payment involves more than taking an action.
Each interaction can involve validation, limits, business rules, regulatory compliance, security, authentication, traceability, availability of funds, fraud monitoring, confirmations, and transaction logging.
That’s why this kind of experience needs a modern architecture underneath it to work properly.
AI may become the new face of customer interaction, but it needs a solid technology foundation to operate reliably.
The integration layer IS critical
One of the biggest challenges for banks will be building a modern integration layer that connects to the core banking system and the systems around it.
Many banks still run on architectures where transactional capabilities are tightly coupled to legacy systems, batch processes, point-to-point integrations, or services that are difficult to reuse.
In a traditional app, this can be manageable because users follow predefined workflows.
In an agentic experience, however, users can express the same intent in many different ways.
The app has to interpret that intent, translate it into a specific action, verify that it can be carried out, query different systems, execute the transaction, and respond clearly.
That requires a well-designed, secure, well-governed API layer aligned with the bank’s actual processes.
Simply “exposing services” only gets you part of the way.
Banks need to design reusable digital capabilities.
For example:
APIs for looking up balances, account activity, payees, limits, products, available payments, fees, transaction statuses, and alerts.
APIs for making transfers and payments, scheduling transactions, changing settings, and authorizing actions.
APIs for verifying identity, assessing risk, checking business rules and consent, and ensuring traceability.
In other words, the banking app of the future needs more resilient integrations.
It has to connect to an architecture that supports real-time, secure, and consistent operations.
What we’ve seen in practice
At WAU, we’ve seen that many financial institutions still run on infrastructure designed for a more traditional model of banking: robust core systems with rigid integrations, reliable transaction processes that aren’t always ready to run in real time, and data models that work for internal operations but may be unable to support more intelligent digital experiences.
Many of those systems have served their purpose well, keeping banking operations stable and reliable for years.
The challenge is that the new digital experience demands something different.
A banking app with agentic AI needs more than screens connected to isolated services. It needs an architecture that can look up information, validate and execute transactions, and send notifications securely, with full traceability and almost immediately.
In our experience, modernization calls for architectural evolution as well as changes in technology.
Banks that want to offer these experiences will need a modern integration layer connected to their core, with well-governed APIs, clean data, and an event-driven transaction architecture.
That’s what will make it possible to move from navigation-based digital banking to intent-based digital banking.
Clean data will be just as important as AI
Data quality will be another critical factor.
An AI agent in a banking app may give a well-written response, but if the information it retrieves is incomplete, duplicated, outdated, or poorly structured, the experience will fall short.
A polished answer alone is unlikely to earn the user’s trust.
It takes a correct answer to earn that trust.
In financial services, accuracy is essential.
If users ask how much they spent, how much they owe, how much they can transfer, or whether they have enough to cover an upcoming obligation, the answer has to be based on reliable, timely, and consistent data.
That’s why many institutions will need to make progress on data governance, catalog cleanup, transaction data standardization, customer data quality, traceability, and integrated data models before pursuing an agentic banking experience.
Good data architecture remains essential with artificial intelligence.
It makes that need more visible.
Toward event-driven banking
Alongside APIs and clean data, there’s another essential component: an event-driven transaction architecture.
Why?
Because agentic interactions won’t always be linear.
A user might request a transfer, then ask to schedule it, change the amount, check whether it will affect their budget, and finally authorize it.
Each step adds context.
Each action can trigger checks.
Each event has to be recorded.
In a modern architecture, events allow different systems to respond independently and in a timely manner.
For example:
- Starting a transfer generates an event.
- Validating the payee generates another.
- Confirming authentication generates another.
- Executing the transaction generates another.
- Notifying the user generates another.
This approach improves traceability and monitoring, makes integrations more flexible, and creates a smoother experience.
It also allows other systems for risk, fraud, analytics, CRM, notifications, and auditing to respond independently of rigid integrations.
Agentic banking calls for more than a new interface.
It requires a new way to orchestrate digital capabilities.
The biggest changes will happen behind the screen
When we think about the future of banking apps, the first thing we’ll probably picture is a modern conversational interface with natural language and intelligent responses.
But the real change will happen beneath the surface.
It will depend on the bank’s ability to turn its processes, data, and systems into reusable digital services.
It will depend on the quality of its data.
It will depend on the security of its integrations.
It will depend on its ability to operate in real time.
And it will depend on whether it is ready to move from rigid architectures to more modular, API-enabled, and event-driven ones.
Agentic AI can transform the end-user experience, but only if financial institutions do the structural work needed to support it.
Otherwise, we’ll have state-of-the-art interfaces connected to processes that are still slow, fragmented, or manual.
That falls short of digital transformation.
It’s just a new visual layer over the same old problems.
Conclusion
The next stage of digital banking will go beyond a better-looking, faster app with more options.
It will mean creating an experience where users can interact with their bank more naturally, in ways that reflect their context and let them complete transactions.
An experience where people can carry out transactions without having to understand the bank’s internal structure.
An experience where technology adapts more readily to what the user wants to do.
To get there, banks will need to modernize much more than the interface.
At WAU, we’ve seen that many financial institutions already have solid systems for running their business, but their architecture isn’t always ready to support intelligent interactions and transactions in real time.
They’ll need to modernize their integration architecture, data, APIs, transaction processes, and ability to handle events in real time.
AI may become the new channel for interacting with customers.
Trust, security, and efficiency will still depend on the architecture behind it.
And perhaps the real challenge is to make banks smarter in the experiences they offer customers and better prepared internally to deliver them.
What do you think?
Are we close to seeing truly agentic banking apps, or is there still work to do to modernize the technology that will make them possible?
